

Best Budget
by CREXIN Technologies
0.0
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 0.0
- Price
- Free
- Download
- 10.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
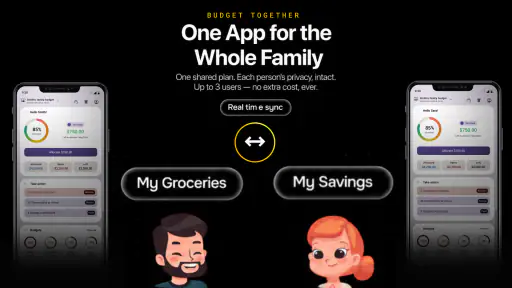
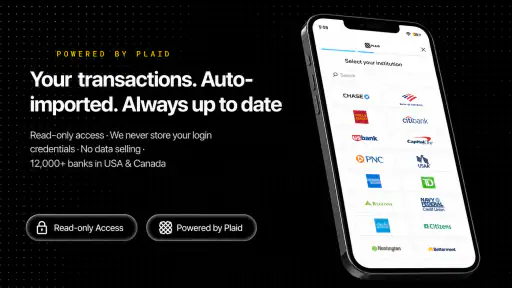
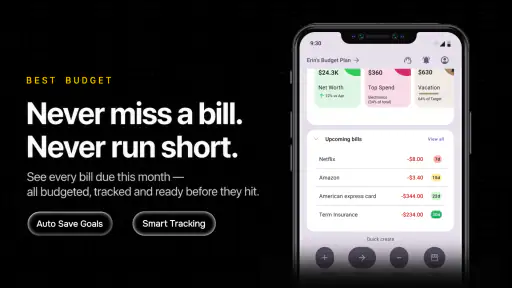
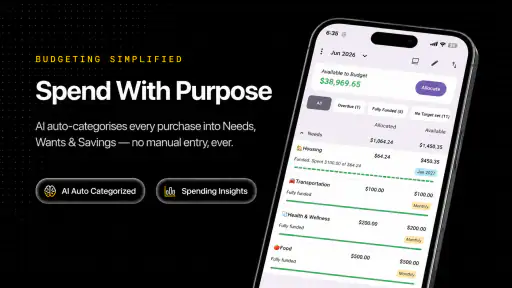
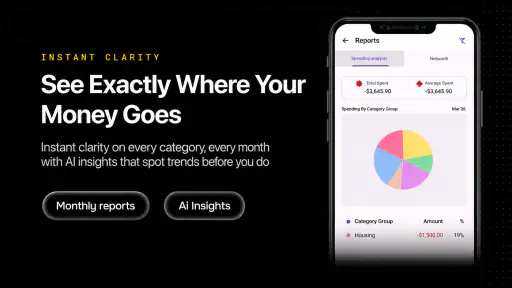
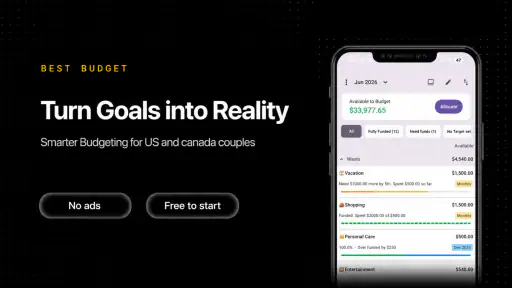
 Analysis by Getfullapps
Managing money sounds simple until small purchases, irregular bills, and debt payments begin competing for the same balance. I used Best Budget as a finance app rather than treating it like a passive expense diary, and its main appeal is clear: it encourages me to connect everyday spending with a practical plan. The app is free to download, aimed at everyone, and developed by CREXIN Technologies. Its purpose is not just to show where money went, but to help me decide where it should go next.
That distinction matters. Many budgeting tools are useful for looking backward, while this one is more interesting when I use it before spending happens. I can think through a monthly limit, separate essential costs from flexible spending, and keep debt repayment or savings in the same conversation. It does not magically solve poor financial habits, but it gives those habits a structure that is easier to revisit.
How Best Budget feels in everyday use
The current release is version 2.1.4, and the app supports devices running Android 8.0 or later. The product is still relatively modest in scale, with more than ten thousand installs, so I approached it as a focused budgeting tool rather than a huge financial platform. That is actually part of its charm: the experience is centered on personal money management instead of trying to become a bank, investment terminal, or social network.
My first useful step was to avoid entering every possible financial detail at once. I started with the categories that affect decisions most often: food, transport, recurring bills, leisure, debt, and savings. This made the budget easier to understand than a long list of narrowly divided categories. If I had separated coffee, takeout, groceries, and restaurants immediately, I might have spent more time maintaining categories than learning from them.
The app works best when I treat each budget as a question. “Can I keep flexible spending under control this week?” is more useful than “Can I make a perfect financial plan?” That approach makes the information actionable. A category that is close to its limit is not merely a warning; it tells me to adjust the next few days before the month becomes difficult.
A realistic example is a month in which rent and utilities are fixed, but food and transportation vary. I can protect the fixed obligations first, then give the flexible categories limits that reflect what is actually available. If an unexpected repair consumes part of the spare money, the important move is not to hide the problem by deleting a category. I would reduce discretionary spending or temporarily lower a savings contribution, then record that decision so the rest of the month remains honest.
Turning a spending log into a decision tool
The strongest workflow I found is a short weekly review. I look at what has already been spent, compare it with the remaining allowance, and ask whether the next week needs a correction. This is more effective than waiting until the end of the month, when the numbers may be accurate but no longer useful. Best Budget is especially suited to this rhythm because its central ideas—tracking, budgeting, debt reduction, and saving—fit together naturally.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
One practical tip is to create a small “irregular costs” allowance instead of pretending every month will be predictable. Annual renewals, school expenses, gifts, and minor repairs can otherwise make a normal budget look like a failure. Reserving room for them gives the plan more resilience. I also prefer to keep debt payments visible as a planned priority rather than treating them as whatever money happens to remain.
Another useful insight is that a budget should show trade-offs, not just restrictions. If I decide to pay extra toward debt, I need to see which flexible category will become smaller. If I increase savings, I should know whether that affects dining out, entertainment, or shopping. The app becomes more valuable when I use it to make those choices deliberately instead of simply reacting to an alarming balance.
Debt and savings require different habits
Debt reduction and saving are often placed next to each other, but they do not behave in the same way. Debt needs consistency and a clear payment priority. Savings benefits from automation in real life, but inside a budgeting routine it also needs a target and a reason. I found it helpful to label each goal by purpose, such as an emergency reserve or a planned purchase, rather than using one vague savings figure.
For someone paying several debts, the app can provide a useful overview, but the user still has to choose a strategy. Paying the highest-interest balance first may reduce long-term cost, while paying the smallest balance first can create faster psychological wins. Best Budget can support the discipline of either approach, yet it should not be mistaken for a financial adviser that decides which method is right for a particular loan arrangement.
The same caution applies to savings. A budget can tell me that a contribution fits on paper, but it cannot guarantee that an emergency will not interrupt it. I would rather set a sustainable amount and preserve the habit than choose an impressive target that forces me to withdraw the money repeatedly. This is one area where the app’s usefulness depends heavily on the quality of the plan I enter.
What has changed for the current release
The confirmed release information places version 2.1.4 in the current product state, following the app’s release on March 9, 2026. That gives existing users a clear reference point when checking whether they are using the current build. I would treat the version as evidence of ongoing maintenance, but not as proof that every personal workflow has been transformed.
For an existing user, the practical question is not whether a newer version sounds important; it is whether the daily routine feels more dependable after updating. I would review the budget categories, recurring plans, debt figures, and savings targets after any update, especially if the app is being used for important monthly decisions. A quick check is sensible before relying on the figures for a bill payment or a major transfer.
New users should begin with a deliberately small setup. Enter the current balance or starting position carefully, define the most important categories, and record a few real transactions before building a complicated system. This makes it easier to notice how Best Budget fits personal habits. It also prevents a common mistake: creating an elaborate budget that is abandoned because maintaining it feels like another unpaid job.
I would also keep a separate record of important account information until I am comfortable with the app’s workflow. That is not a criticism unique to this product; it is a sensible precaution with any financial organizer. A budgeting app helps me understand and plan, but it should not be the only place where I remember a payment date, account number, or debt agreement.
Where the app is more useful than a spreadsheet
A spreadsheet remains a strong alternative for people who enjoy designing their own formulas and reports. It can handle unusual income patterns, shared household calculations, and custom projections with almost unlimited flexibility. However, that flexibility comes with maintenance. I have to build the categories, formulas, summaries, and reminders myself, and a spreadsheet does not automatically become easier to use just because it is powerful.
Best Budget is the better choice for someone who wants a ready-made budgeting mindset without learning spreadsheet design. Its focused purpose reduces the number of decisions I need to make before I can start. The trade-off is control: users who want elaborate forecasting, detailed investment tracking, or a highly customized household ledger may outgrow a focused app.
It also occupies a different space from a banking app. A bank application is usually the place to view balances, move money, and manage accounts. A budgeting app is where I interpret those transactions and decide what they mean for future spending. Best Budget should complement that process rather than replace the bank’s official records.
Compared with a paper notebook, the app offers a more structured way to connect categories with goals. Paper can be wonderfully quick and private, but it is harder to revise when plans change or to compare several priorities at once. Someone who enjoys writing every purchase by hand may still prefer a notebook, particularly if the act of writing is what keeps them attentive. Best Budget is more suitable for the person who wants a repeatable digital review.
Limitations worth considering before committing
The biggest limitation is the need for regular input and honest interpretation. No budgeting screen can recognize that a purchase was emotionally driven, decide whether a subscription is worthwhile, or know that an upcoming family event will change the month. If I stop recording expenses, the plan can look healthy while reality moves in another direction.
There is also a difference between tracking spending and importing a complete financial life. Users who expect a full banking dashboard, investment analysis, automated bill negotiation, or professional debt advice may find the app too narrow. Its value is strongest for deliberate personal budgeting, not for replacing every financial service.
Although the app is free, in-app purchases range from six dollars to ninety-six dollars per item. That makes it important to understand which parts of the experience require payment before building a routine around them. A free starting point is attractive, but a user should evaluate the ongoing cost of any optional upgrade against the actual benefit it provides. For basic budgeting, I would begin with the free experience and only consider paying if a specific limitation affects my routine.
The age classification is Everyone, which makes the app broadly approachable. That does not mean every financial decision is suitable for every user, of course. A teenager learning to separate spending from saving may find the structure helpful, while a person dealing with complex taxes, business finances, or legal debt arrangements should use more specialized guidance alongside any app.
Who should use it, and who should skip it
I would recommend Best Budget to someone who repeatedly wonders where the month’s money went and wants a simple place to turn that frustration into a plan. It is also a good fit for a person starting debt repayment, a couple trying to agree on spending limits, or a saver who needs a visible goal rather than a vague intention.
It is particularly useful for people willing to perform a short weekly check-in. That habit is the difference between a living budget and a forgotten setup screen. If you are comfortable making small adjustments as circumstances change, the app can become a practical companion rather than a judgmental scorecard.
I would skip it if you want automatic, hands-off financial management. I would also look elsewhere if your main need is investment performance, business accounting, tax preparation, or detailed account aggregation. A spreadsheet may be better for custom models, a bank app may be better for transactions, and a specialist debt service may be more appropriate for complicated repayment problems.
What I would watch as the product develops
Because version 2.1.4 is the current reference point, I would watch how CREXIN Technologies continues to balance simplicity with depth. The most valuable future direction would be improvements that make regular reviews faster without turning the app into a crowded financial dashboard. Clearer handling of irregular expenses, flexible income, shared budgets, and long-term goals would matter more to me than decorative changes.
I would also pay attention to how the app handles the boundary between encouragement and overconfidence. Budgeting guidance should help users act, but it should not make uncertain financial situations appear solved. The best evolution would preserve the approachable feel while giving experienced users enough control to manage changing priorities.
For now, my advice is to judge the app after using it through a complete budgeting cycle rather than after the first setup. Start with a few meaningful categories, record transactions consistently, review the plan once a week, and test whether the debt and savings goals influence real decisions. That process will reveal more than a quick glance at the interface.
Overall, Best Budget is a focused finance app with a sensible purpose and a useful emphasis on linking spending with debt and savings. I like it most as a planning companion for ordinary households, not as an all-in-one financial command center. Its free entry point makes it easy to try, while the optional purchases mean I would examine the upgrade value carefully. If you want a manageable routine and are prepared to participate in it, this is a promising choice; if you want automation or advanced financial analysis, a different tool will likely serve you better.
Pros
- Simple interface makes budgeting easy for beginners.
- Helps track spending and identify where money goes.
- Useful for setting limits across different expense categories.
- Supports better saving habits through regular budget monitoring.
- Lightweight design should run smoothly on most modern devices.
Cons
- May feel too basic for users needing advanced financial analysis.
- Manual expense entry can become time-consuming over time.
- Limited features may not suit complex household budgets.
- Budget accuracy depends on consistently recording every transaction.
- Some useful tools may require payment or premium access.
FAQs for Best Budget
What is Best Budget, and what can I use it for?
Best Budget is a personal finance app designed to help you organize income, expenses, bills, and savings goals in one place. After setting up your accounts and spending categories, you can record transactions, review where your money goes, and monitor your available balance. It is useful for everyday budgeting, although it should not be treated as a replacement for professional financial advice.
Is Best Budget free to download and use?
The availability of free features, premium tools, subscriptions, or one-time purchases may depend on the version of Best Budget and the platform you use. Before downloading, check the current Google Play or App Store listing for pricing details. If the app offers optional paid features, review the subscription terms carefully, including renewal conditions, trial periods, and cancellation instructions.
Does Best Budget connect directly to my bank accounts?
Best Budget may support manual transaction entry, while some versions or comparable budgeting services can offer account synchronization through third-party financial connections. Availability depends on your country, bank, and the specific app version. If you connect an account, read the privacy policy and permissions carefully. Manual tracking may be preferable if you do not want to share banking access.
Is my financial information safe in Best Budget?
Before entering sensitive financial information, review Best Budget’s privacy policy, security practices, and requested permissions. Avoid storing unnecessary details such as full card numbers, passwords, or banking credentials unless the app clearly explains how they are protected. Use a strong device passcode and enable biometric protection when available. No budgeting app can guarantee complete protection from every security risk.
Can I use Best Budget without an internet connection?
Many budgeting apps allow you to view or enter basic information while offline, but features such as synchronization, backups, account connections, advertisements, or cloud access may require an internet connection. Offline behavior can vary between Android and iOS versions. If reliable access is important to you, test the app after installation and confirm how your entries are saved and synchronized.

Best Budget
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@bestbudget.in, visit https://bestbudget.in, or review their https://www.bestbudget.in/privacy-policy.










